Dollar Power Abroad: How Savvy Americans Are Using Currency Advantages to Fund Residency Investments at a Fraction of the Cost
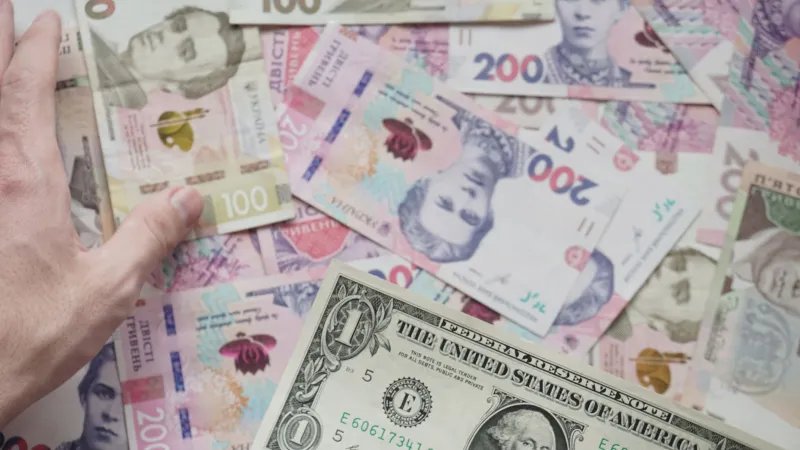
For most Americans, the phrase "investment migration" conjures images of wire transfers, legal fees, and bureaucratic complexity. What rarely enters the conversation is one of the most powerful financial levers available to US-based investors pursuing residency abroad: the structural advantage of holding dollars in a world where many residency-qualifying investments are denominated in weaker currencies.
This is not a loophole. It is not tax evasion. It is the deliberate, legal application of macroeconomic realities to a personal wealth and mobility strategy. When executed thoughtfully, currency arbitrage within the context of investment residency can reduce your effective capital outlay, accelerate portfolio growth in foreign markets, and create a diversified asset base that functions across multiple economic environments.
Understanding the Core Concept: What Currency Arbitrage Actually Means for Investors
In its simplest form, currency arbitrage in the context of residency investment refers to the practice of deploying US dollars—one of the world's reserve currencies—into markets where the local currency trades at a meaningful discount. The result is that your purchasing power, measured in real assets, is substantially greater than the nominal investment figures suggest.
Consider a practical illustration. Portugal's Golden Visa program has historically required minimum real estate investments in qualifying areas. An American investor converting dollars to euros during a period of dollar strength effectively acquires the same qualifying asset at a lower real cost than a European counterpart purchasing in their home currency. The legal residency threshold remains identical; the financial burden does not.
This dynamic is even more pronounced in markets outside the eurozone. Countries like Paraguay, Panama, Colombia, and Georgia—all of which offer legitimate residency pathways—operate in currencies that have historically traded at substantial discounts to the dollar. The arithmetic, in these cases, can be striking.
Which Markets Offer the Strongest Currency Advantage for American Investors?
Not every residency jurisdiction presents a meaningful currency arbitrage opportunity. The analysis requires evaluating three variables simultaneously: the strength of the local currency relative to the dollar, the structure of the residency investment requirement, and the underlying quality of the asset being acquired.
Latin American Markets
Panama stands out for several reasons. The Panamanian balboa is pegged 1:1 to the US dollar, which eliminates currency conversion risk while still offering a cost-of-living environment that is considerably lower than most major American cities. For investors seeking predictability, this peg provides stability while the broader economic environment allows investment capital to generate returns that would be difficult to replicate domestically.
Colombia's residency-by-investment program requires a minimum investment threshold denominated in Colombian pesos. For dollar holders, this threshold has represented exceptional value during periods of peso depreciation. Real estate in Medellín and Bogotá, in particular, has attracted significant American investor attention precisely because the combination of currency advantage and rising local property values creates a dual return mechanism.
Paraguay offers one of the most straightforward passive residency programs in the Western Hemisphere, with minimal investment requirements and a currency—the guaraní—that has historically provided favorable conversion rates for dollar-denominated capital.
Eastern European and Caucasus Markets
Georgia, situated at the crossroads of Europe and Asia, has emerged as a particularly compelling destination for American investors. The Georgian lari trades at a significant discount to the dollar, and the country's residency programs are accessible at relatively modest investment thresholds. Georgia's flat tax structure and territorial tax system add a further layer of financial efficiency for Americans who structure their affairs appropriately.
Several Balkan nations—including Albania and North Macedonia—are developing investment residency frameworks that combine euro-adjacent economic environments with local currency dynamics that favor dollar-holding investors.
Structuring Investments to Maximize Purchasing Power Across Jurisdictions
Identifying favorable currency environments is only the first step. The structure of your investment matters as much as the location. American investors pursuing residency through real estate, business formation, or government bond purchases should work with advisors who understand both the local legal framework and the cross-border tax implications of holding assets in foreign currencies.
Several structural considerations deserve attention:
Asset denomination and repatriation planning. When an asset is acquired in a foreign currency, any eventual sale generates a gain or loss that must be calculated in US dollars for federal tax purposes. This means that even a flat local-currency return can produce a taxable gain if the dollar has weakened against the local currency during the holding period—or a deductible loss if the opposite has occurred. Planning for this dynamic from the outset is essential.
Entity structure. Holding foreign real estate or business interests through properly structured entities—whether domestic LLCs, foreign corporations, or treaty-compliant arrangements—can significantly affect both your tax exposure and your residency qualification. The wrong structure can inadvertently trigger Passive Foreign Investment Company (PFIC) rules or Controlled Foreign Corporation (CFC) reporting obligations under US law.
Timing of capital deployment. Currency markets move. An investor who monitors exchange rate trends and times their capital conversion strategically can capture additional purchasing power beyond what the baseline arbitrage opportunity provides. This is not speculation in the traditional sense; it is prudent financial planning applied to a real-asset acquisition strategy.
Tax Implications: What Every American Must Understand Before Moving Capital Abroad
The United States taxes its citizens on worldwide income, regardless of where they reside. This fundamental reality shapes every cross-border investment strategy and demands careful attention from Americans pursuing residency abroad.
Foreign currency gains are generally treated as ordinary income under US tax law, not capital gains. This distinction carries meaningful consequences for investors who hold foreign-currency-denominated bank accounts, bonds, or receivables. Gains arising from currency fluctuation on these instruments are reported on your federal return and taxed at ordinary income rates.
Foreign real estate, by contrast, is typically treated as a capital asset, with gains subject to capital gains rates upon disposition. However, depreciation recapture rules, Foreign Investment in Real Property Tax Act (FIRPTA) considerations for certain transactions, and the interaction with foreign tax credits all create complexity that requires professional guidance.
For investors who eventually establish genuine tax residency abroad—moving beyond a simple investment residency to becoming a bona fide resident of a foreign country—the Foreign Earned Income Exclusion and the Foreign Tax Credit become relevant tools for managing US tax exposure. The strategic sequencing of these elections, in combination with treaty provisions where applicable, can meaningfully reduce the overall tax burden on cross-border investment returns.
Building a Durable Portfolio, Not Just a Residency
The most successful investment migration strategies treat residency as one component of a broader wealth-building framework, not as an end in itself. Currency arbitrage, properly applied, is a means of acquiring higher-quality assets, in better locations, at lower effective costs—assets that continue to generate returns long after the residency certificate has been issued.
Americans who approach this process with the discipline of portfolio construction rather than the urgency of immigration will find that the financial case for cross-border investment residency is compelling on its own terms. The mobility and optionality that residency provides are, in this framing, an additional return on a well-structured investment.
The dollar remains a formidable tool in global markets. The question is whether you are putting it to work.