Rate Cuts on the Horizon: Why the Fed's Next Move Could Cost American Residency Investors Dearly
For Americans evaluating residency-by-investment programs, the conversation typically centers on destination countries, minimum capital thresholds, and processing timelines. Rarely does the discussion begin with the Federal Reserve. Yet the Fed's monetary policy decisions — specifically, the timing and pace of interest rate reductions — may be among the most consequential variables determining how much it costs an American to secure foreign residency in 2025 and beyond.
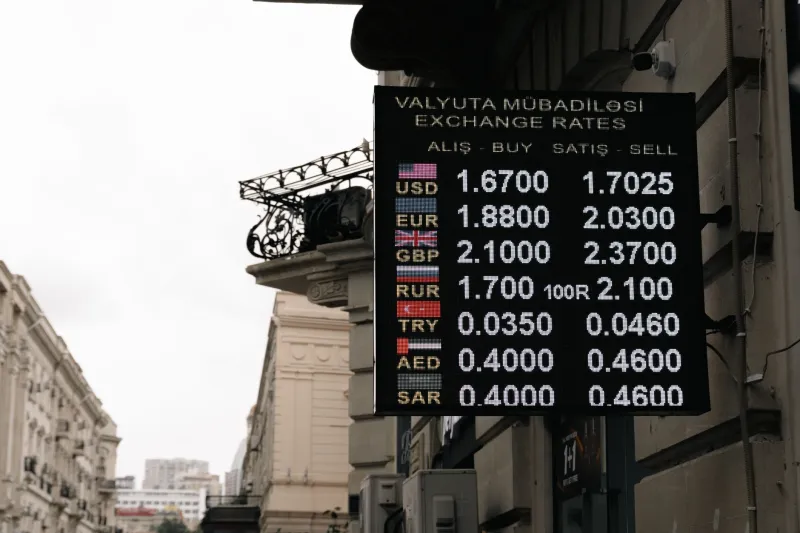
The connection is not abstract. It operates through a mechanism that any investor familiar with currency markets will recognize immediately: when U.S. interest rates fall relative to those of other developed economies, the dollar weakens. And when the dollar weakens, every euro, pound, or dirham-denominated investment minimum becomes more expensive in real terms for American buyers.
For those considering programs in Portugal, Greece, the UAE, or elsewhere, this is not a theoretical risk. It is a ticking clock.
How Interest Rate Differentials Move the Dollar
The relationship between interest rates and currency strength is one of the more reliable dynamics in international finance. Higher domestic interest rates attract foreign capital seeking yield, which increases demand for the domestic currency and pushes its value upward. Conversely, when a central bank cuts rates, the yield advantage narrows, capital flows shift, and the currency typically depreciates against peers maintaining higher rates.
The Federal Reserve held rates at elevated levels throughout much of 2023 and 2024 as part of its campaign to bring inflation under control. During that period, the U.S. dollar strengthened considerably against a basket of major currencies, including the euro. That strength translated directly into purchasing power for Americans looking to deploy capital abroad — effectively discounting the entry cost of foreign residency programs denominated in non-dollar currencies.
As the Fed signals a pivot toward lower rates, that discount begins to erode. The question for American residency investors is not whether the dollar will weaken, but how quickly — and whether they will have acted before it does.
What a 10–15% Dollar Decline Actually Means for Residency Thresholds
Consider a concrete example. Several of Europe's most sought-after residency programs require minimum real estate or fund investments in the range of €250,000 to €500,000. At a EUR/USD exchange rate of 1.08, a €500,000 investment costs an American approximately $540,000. If the dollar weakens to 1.20 against the euro — a shift well within historical norms following a Fed easing cycle — that same investment now costs $600,000. That is a $60,000 increase driven entirely by macroeconomic timing, with no change in the underlying program requirements.
For programs in the Middle East or Southeast Asia, similar dynamics apply, though the mechanisms differ depending on whether local currencies are pegged, managed, or freely floating. Even in managed currency environments, dollar weakness tends to manifest through related asset price inflation, particularly in real estate markets where foreign demand is concentrated.
The arithmetic is straightforward. A six-to-twelve-month delay in executing a residency investment, if it coincides with a meaningful Fed easing cycle, could add tens of thousands of dollars to the effective cost of entry — without any corresponding increase in the benefits received.
The Compounding Effect: Currency Moves and Rising Program Thresholds
Currency depreciation does not operate in isolation. It compounds with a separate trend that has been accelerating across residency markets: the systematic increase of minimum investment thresholds by host governments.
Portugal restructured its Golden Visa program significantly in recent years, eliminating residential real estate as a qualifying investment category in many regions and raising thresholds in others. Greece doubled its minimum investment requirement in high-demand areas. Spain's program has faced political headwinds that could result in further changes. The pattern across Europe and beyond is consistent — programs that were once accessible at lower entry points are becoming more expensive by design, as governments respond to housing market pressures and tighten the criteria for participation.
An American investor who delays entry by twelve months may therefore face a dual cost increase: a weaker dollar that raises the effective price of a foreign-currency investment, layered on top of a formally higher minimum threshold set by the host country. These two forces do not merely add — they multiply.
Why the Current Window Remains Meaningful
Despite the headwinds accumulating on the horizon, the present moment retains genuine advantages for Americans prepared to move decisively. The dollar, while off its recent peaks, remains historically strong against several currencies relevant to investment migration. Real estate valuations in certain qualifying markets have moderated from post-pandemic highs, creating more attractive entry points than existed twelve to eighteen months ago. And many programs — including fund-based options in Europe and real estate pathways in the Caribbean and Middle East — continue to offer terms that are unlikely to remain unchanged as global economic conditions evolve.
For investors who have been conducting due diligence, consulting with immigration attorneys, and evaluating program structures, the strategic imperative is to compress the timeline between evaluation and execution. The window does not close all at once. It narrows gradually, then suddenly.
Positioning Capital Before the Shift
The practical implication for American investors is not to act recklessly or to compress due diligence in ways that create legal or financial risk. It is to treat macroeconomic timing as a legitimate input in the decision-making process — one that deserves the same analytical rigor applied to program selection, legal structuring, and tax planning.
This means engaging qualified legal counsel and financial advisors who understand both the residency landscape and the currency dynamics at play. It means identifying target programs and jurisdictions now, rather than after the Fed has already moved. And it means understanding that in investment migration, as in most markets, the investors who benefit most are those who recognize inflection points before they become consensus.
The Federal Reserve's rate decisions are not made with the residency investor in mind. But their consequences ripple outward into every dollar-denominated calculation an American makes when investing abroad. For those serious about securing residency through investment, the Fed's next move is not background noise. It is the starting gun.
Invest to Migrate provides editorial content for informational purposes only. Nothing in this article constitutes legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making investment or immigration decisions.