Splitting the Difference: How Multi-Jurisdictional Residency Lets Americans Legally Optimize Taxes Across Borders
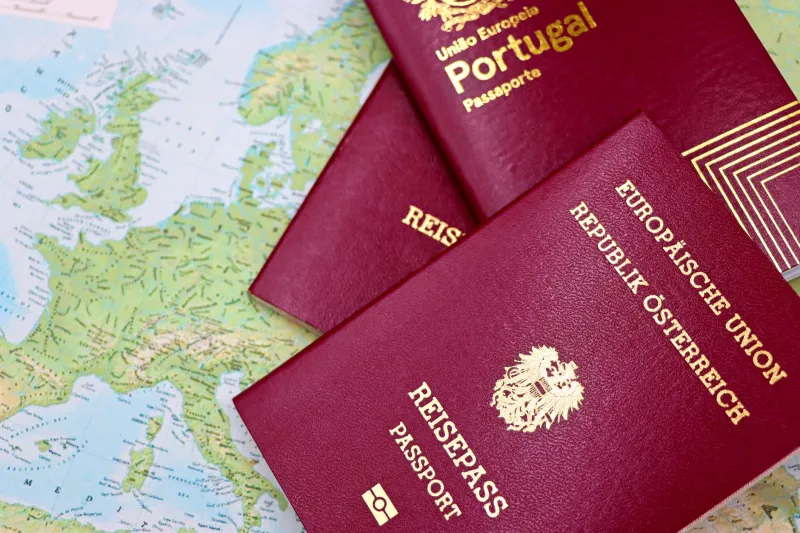
For most Americans, taxes are a fixed reality — an obligation calculated in one currency, reported to one government, and paid under one set of rules. But a sophisticated and growing class of investors, entrepreneurs, and mobile professionals is quietly rewriting that assumption. By establishing legal residency in two or more countries simultaneously, they are not evading taxes. They are engineering their financial lives to sit at the intersection of multiple legal frameworks — and capturing the advantages that exist precisely where those frameworks diverge.
This is residency arbitrage. And done correctly, it is entirely lawful.
What Residency Arbitrage Actually Means
The term "arbitrage" typically describes the practice of exploiting price differences across markets. In the context of global residency, the "price" being arbitraged is the effective tax rate — and the "markets" are sovereign nations, each with its own rules governing how income, capital gains, corporate profits, and investment returns are taxed.
An American citizen who establishes legal residency in Portugal, for instance, may qualify for that country's Non-Habitual Resident (NHR) regime, which historically offered flat-rate taxation on foreign-sourced income for a ten-year period. A separate residency in a Gulf Cooperation Council state — the UAE being the most prominent example — can serve as the anchor for a holding company structure in a zero-income-tax environment. Meanwhile, the investor's U.S. obligations remain governed by the Foreign Earned Income Exclusion (FEIE) and the foreign tax credit framework under the Internal Revenue Code.
None of these arrangements, in isolation, constitutes tax evasion. The complexity — and the opportunity — lies in how they interact.
The Entrepreneur's Playbook: Splitting Active and Passive Income
Consider a practical scenario that has become increasingly common among American founders and consultants. An entrepreneur generates two distinct income streams: active consulting revenue earned through client engagements, and passive investment income from a portfolio of dividend-paying equities and short-term rental properties.
Under a purely U.S.-based tax structure, both streams are subject to federal income tax, self-employment tax on the active income, and potentially state income tax depending on domicile. The combined marginal rate for a high earner can approach or exceed 50 percent in states like California or New York.
By establishing a genuine second residency — through, for example, Portugal's D8 Digital Nomad Visa or Spain's Beckham Law regime — the entrepreneur can potentially route the active consulting income through a foreign structure and treat it under a more favorable foreign tax framework, while simultaneously claiming the FEIE on qualifying earned income. The passive investment income, meanwhile, may be structured through a holding entity in a jurisdiction with favorable capital gains treatment or a territorial tax system.
The critical distinction here is substance. Tax authorities on both sides of the Atlantic scrutinize arrangements where residency is claimed on paper but not lived in practice. Physical presence requirements, local banking relationships, genuine business activity, and documented ties to the jurisdiction are all factors that determine whether a residency claim will withstand scrutiny.
Capital Gains Timing: A Strategy Often Overlooked
One of the most underappreciated dimensions of multi-jurisdictional residency is the ability to time the recognition of capital gains in a jurisdiction where the applicable rate is lower — or where an exemption applies.
Several EU member states, including Belgium and the Netherlands, do not impose capital gains taxes on private individuals selling shares in qualifying companies, provided certain holding period and substance requirements are met. An American investor who has established genuine residency in such a jurisdiction and structured their equity holdings appropriately may be able to realize a significant liquidity event — a company exit, a large portfolio rebalancing — at a materially lower effective rate than would apply under U.S. law alone.
This is not a loophole. It is the deliberate application of treaty provisions, domestic exemptions, and residency rules that have existed for decades. The sophistication lies in recognizing the opportunity and structuring affairs well in advance of the triggering event.
The Business Deduction Dimension
Beyond income and gains, residency arbitrage offers meaningful advantages in the treatment of business deductions. Different jurisdictions define deductible business expenses with varying degrees of generosity. Research and development credits, home office deductions, vehicle and travel expenses, and entertainment costs are all treated differently across tax regimes.
An American business owner who operates a genuine enterprise with employees or contractors in a second jurisdiction may be entitled to deduct expenses under that country's corporate tax framework that would be disallowed or limited under U.S. rules. When a foreign tax credit is applied against the U.S. tax liability, the net effect can be a meaningfully lower combined tax burden — achieved entirely through legitimate structural planning.
The key phrase, again, is "genuine enterprise." Shell structures with no real employees, no physical operations, and no economic substance are precisely what the OECD's Base Erosion and Profit Shifting (BEPS) framework was designed to dismantle. Sustainable residency arbitrage is built on real business activity and real physical presence.
What the Case Studies Reveal
Across the investor community, patterns are emerging. Technology founders who have taken early liquidity from startup exits are establishing residency in low-capital-gains jurisdictions before their next venture reaches exit stage. Real estate investors are pairing U.S. depreciation deductions with foreign rental income structures that benefit from territorial tax treatment. Retirees with substantial investment portfolios are relocating to countries with favorable pension and dividend tax treaties with the United States.
In each case, the common thread is advance planning. Residency arbitrage is not a retroactive fix. It requires restructuring affairs — sometimes years before a major income event — to ensure that the legal and physical substance of each residency claim is unassailable.
The Compliance Imperative
It would be irresponsible to discuss this strategy without addressing its compliance demands. American citizens remain subject to U.S. worldwide income taxation regardless of where they live. FBAR filings, FATCA reporting, Form 8938, and the complex rules governing Passive Foreign Investment Companies (PFICs) and Controlled Foreign Corporations (CFCs) create a web of obligations that must be navigated with precision.
The cost of non-compliance — civil penalties, criminal exposure, reputational damage — far exceeds any tax savings achieved through careless structuring. Every multi-jurisdictional arrangement of this nature requires a team that includes a U.S. international tax attorney, a local tax advisor in each residency jurisdiction, and ideally a cross-border financial planner who understands how the pieces interact.
The Strategic Takeaway
Residency arbitrage is not a strategy for everyone. It demands genuine mobility, meaningful upfront investment — both in the residency programs themselves and in professional advisory fees — and a long-term commitment to maintaining the substance that legitimizes the structure.
But for the American investor or entrepreneur who is already considering global mobility, the tax dimension of that decision is far too significant to treat as an afterthought. The jurisdictions are different. The rules are different. And the opportunities, for those who plan carefully, are very real.